




Our investment team is closely monitoring the developments in the Middle East and the impact they are having on commodity prices, the stock market, and the world economy. We lament the loss of innocent life, pray for the safety of U.S. troops in harm’s way and mourn the U.S. military servicemembers who have lost their lives.
You will continue to hear from us on the conflict with Iran. In the meantime, if you have any questions on the markets and the economy or if there is anything we can do to support you and your clients during this difficult time, please reach out to us via our Investment Strategy Team’s email address at opsresearch@orion.com.
Weekly Notes from Tim
By Tim Holland, CFA, Chief Investment Officer
- The older I get the faster the calendar pages turn – the fact that my children are turning 20 and 17 is a bit terrifying, but as Woody Harrelson’s character in True Detective puts it, “Father Time has his way with us all,” and since we can’t fight the calendar we might as well use milestones to reflect on where we were, how far we have come and where we might be headed, and this week we would like to do that with our bull market, which celebrated its 4th birthday on October 12th.
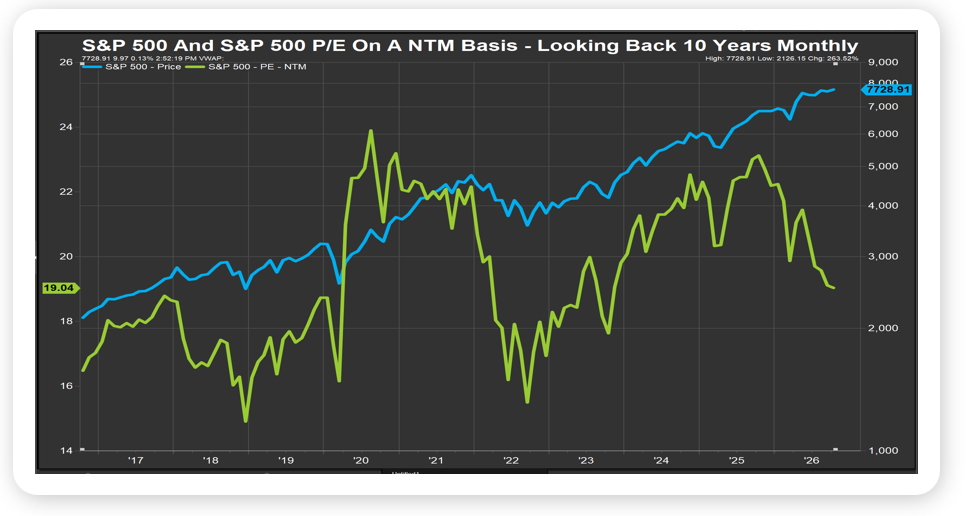
- As to where we were…in October 2022, US inflation was running in the high single digits, the loftiest levels since the early 1980s; the S&P 500 had fallen about 26% from its early 2022 peak; the Fed had been slow to respond to the post-pandemic spike in prices but once it started raising rates, did so in rapid fashion; the world was still grappling with Russia’s invasion of Ukraine; investor sentiment was in the doldrums and the S&P traded just shy of 16x earnings (see chart).
- As to how far we have come….since late 2022, the S&P 500 is up approximately 121% with the biggest driver of market gains being above trend earnings growth driven by the commercialization of AI and the AI infrastructure build out (interestingly enough, ChatGPT was released to the public one month on from the stock market bottom); beyond the AI trade, we had the Fed pivot from rate hikes to rate cuts (setting aside the September 2026 quarter point rate increase); the extension of the 2017 tax cuts and a fiscal policy pivot that highly incented companies to invest in productive assets, and inflation falling to the low single digits.
- As to where we might be headed…we first want to note market gains in the face of a heated 2024 Presidential Election; trade policy uncertainty; historically negative consumer sentiment; elevated price levels post-pandemic and a war in the world’s most geo-politically sensitive region, among other headwinds. Going forward, we think the AI cap ex cycle will persist and with-it strong revenue and earnings growth; inflation should get better, or at least not get worse and any Fed tightening cycle should prove short lived. Finally, over the past 80 years, 50% of bull markets that celebrated a 4th birthday went on to celebrate a 5th.
Sources: FactSet October 2026
Looking Back, Looking Ahead
By Ben Vaske, CFA, Manager, Investment Strategy
Last Week
Last week was one of the sharpest single-week growth versus value divergences of the year. The NASDAQ 100 fell roughly 5.5% and U.S. growth stocks dropped nearly 7%, led by a more than 11% decline in the PHLX Semiconductor index, its worst weekly performance since April 2025. Value gained nearly 2.5%, while the Dow added just under 1%. International markets were mixed, with developed international gaining nearly 1.5% while emerging markets fell over 5% in conjunction with the domestic tech selloff. The selloff followed the S&P 500 snapping a 53-day streak without a 1% daily decline, one of the ten longest such streaks in market history.
Fixed income was a relative bright spot, with the Bloomberg Agg gaining nearly 1% as Treasury yields retreated from their recent highs.
On the inflation front, CPI rose 0.6% in September and came in at 3.7% year-over-year, just expectations, while PPI rose 1.3% on the month and 6.3% over the past year, well above the 5.5% consensus. Energy prices were the primary driver in both cases, though core CPI also ran hotter than expected for the second consecutive month, marking the 66th straight month that both headline and core inflation have exceeded the Fed's 2% target. Retail sales beat expectations at 0.8%, though most of the upside came from higher prices at the pump rather than broad-based consumer strength. Real inflation-adjusted hourly earnings declined 0.5% in September and are now down 0.7% over the past year, a meaningful headwind to consumer purchasing power.
This Week
Q3 earnings season moves into full gear with Tesla, SpaceX, and Netflix all reporting, headlining what becomes one of the busiest stretches of the quarter over the coming weeks. The economic calendar is lighter, with flash PMIs and consumer sentiment on Friday as the primary releases. The October 28th FOMC meeting is now just over a week away, with markets pricing an 85% probability of a hold and a 15% chance of another hike as the Fed weighs persistent above-target inflation against a softening labor market.